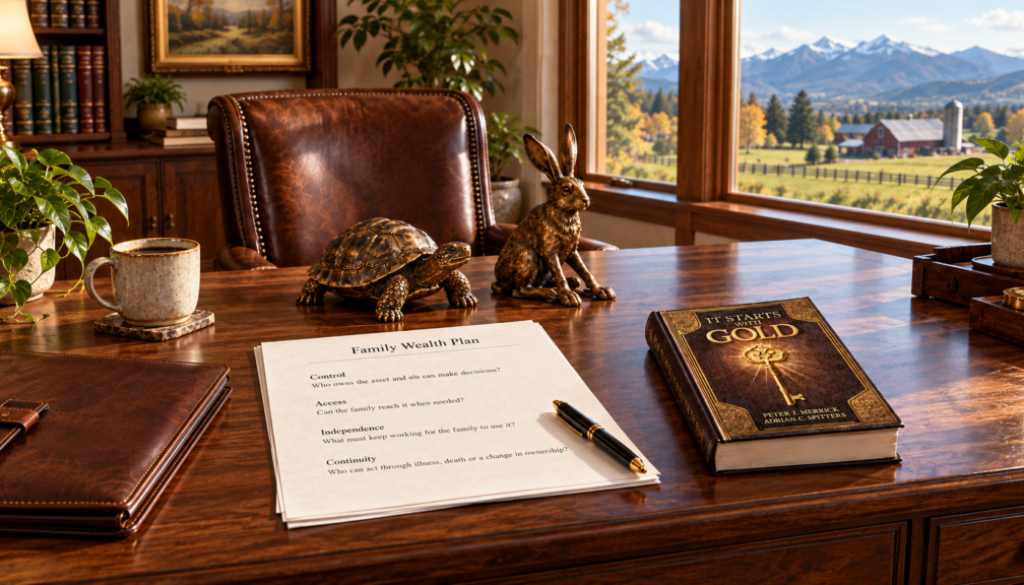
The Tortoise and the Hare
Protecting your family’s wealth when markets fall or access is blocked
By Adrian C. Spitters, CFP®, FCSI®, CEA and Peter J. Merrick, TEP®, Co-Authors, It Starts With Gold™ | Co-Creators, The Merrick Spitters Reset Report™
Your family’s bills will not wait for markets to recover or bank access to return. Retirement income, payroll and farm or business costs still come due.
Families who fear financial collapse, bank confiscation or government overreach deserve clear answers. I favour a plan that tests those risks and preserves your ability to act.
The hare in the fable trusts its early lead and stops before the race is over. The tortoise keeps moving towards the finish line. In investing, the hare chases rising prices and panics when fear takes over. The tortoise prepares before trouble arrives and acts when the evidence calls for a change.
What I Learned in 1999 and 2000
I entered this business in 1987. I wrote my licensing examination during the weekend of the Black Monday crash. Nearly four decades of market cycles have taught me to trust a sound process more than a confident forecast.
During 1999, I began moving all my clients out of technology mutual funds because I was concerned about prices that the underlying businesses could not justify. By early 2000, before the technology market peaked, those moves were complete. My clients held financial mutual funds, including Canadian financial funds, along with resource, precious-metals and infrastructure mutual funds. My clients avoided the technology-led market crash of 2000–2002. Not a single client lost money during that downturn.
That was a tortoise decision: change course when prices no longer make sense. The hare sees rising returns and assumes they will continue. The tortoise examines the price, the business and the family’s needs, then acts on what the evidence shows. A disciplined process must allow a change in direction.
I judge today’s AI overvaluations to be significantly worse than those of the dot-com era. This race combines high share prices, huge spending commitments, growing debt and dependence on power and equipment that are already in short supply. I see reckless expansion at all costs.
Companies are racing to dominate the AI era while power, equipment and material shortages threaten their plans. I expect the rewards to concentrate among a handful of winners. A July 2026 paper published by the Bank for International Settlements models how this competition can drive excessive spending. Its baseline estimates investment about 50 percent above the level that would make the best use of resources.
S&P Global documents shortages in transformer steel, memory and other essential inputs. Sightline Climate estimated in February 2026 that 30–50 percent of data centre capacity scheduled for that year could miss its delivery date. Columbia professor Stijn Van Nieuwerburgh’s Brookings paper examines how debt and complex financing can spread losses to lenders and investors. Delayed projects still carry financing costs. Hardware can become outdated before the expected revenue arrives.
I expect projects to be scaled back or abandoned as this race unfolds. The technology can succeed while investors lose money backing businesses that spend too much or fall behind. The hare focuses on who could win the AI race. The tortoise asks how much of the family’s retirement depends on those companies delivering the profits already built into their share prices. A sector setback can become a retirement spending problem or consume the reserve meant to carry a business through a slow year.
Start With Asset Security
I use Owning Assets in Order of Asset Security™ to examine how a family owns and uses its wealth. Four questions guide that review:
Control: Who owns the asset, who holds it and who can make decisions about it?
Access: Can you reach the asset when you need it, including during a crisis?
Independence: What must keep working outside your control for you to use the asset?
Continuity: Can control pass to the right people through illness, death or a change in ownership?
Apply these questions to your bank accounts, investments, land and business. An advertised return may be enough for the hare. Before committing money, the tortoise examines the ownership and access arrangements that must support the family’s plan.
Prepare for Market and Banking Disruptions
A market crash reduces asset values. A bank failure concerns repayment. An account freeze blocks access. Your family needs a response suited to each risk.
During Canada’s 2022 emergency measures, financial institutions froze accounts linked to the protests. In 2024, the Federal Court found the government’s use of the Emergencies Act unlawful. It also found the financial measures violated Charter protection against unreasonable search and seizure. The Federal Court of Appeal upheld the ruling in January 2026. A later ruling could not undo the disruption for families shut out of their money. Payroll, mortgage payments and operating bills still need to be paid while access is blocked. Restoring access does not automatically rebuild trust.
Canada’s bail-in rules allow certain eligible bank debts to be converted into shares. Review the legal terms attached to what you own and how a bank resolution would affect it. An account freeze requires its own access plan.
Consider a farming or business-owning family with land, an operating business and retirement savings. It takes the tortoise’s approach by keeping cash for bills and operating costs separate from the retirement portfolio. A farm needs money for feed, fuel and wages before the next sale. Land value cannot settle those bills until money can be raised against it or a sale is completed.
Now suppose a banking disruption blocks the account used for payroll. Review how much you rely on one bank, what other lawful payment methods are available and who can act. A second account at the same bank still depends on that bank’s systems. For a government freeze, review the legal reach of the order before treating an account elsewhere as a backup. Keep the records needed to use those arrangements.
Physical gold requires clear ownership, secure storage and a workable way to reach or sell it. A family cannot pay urgent bills with metal it cannot access. Record the instructions and make sure the people who may need to act know where to find them.
Peter J. Merrick and I wrote about these questions in It Starts With Gold™, our novel rooted in monetary history. Gold is the starting point for examining who owns an asset, who controls it and whether a family can reach it. The tortoise applies those questions before a crisis, then carries the same discipline across the family’s wealth.
Test the Warning and the Proposed Solution
Serious threats to your family’s wealth deserve serious attention. Fear can also sell newsletters, subscriptions and investments. A frightening forecast sets the hare’s pace. Before reacting, the tortoise asks what supports the warning, how the threat could affect the family’s wealth and whether the proposed solution would work if the threat materialized. Ask what could block access, what new risks the solution creates and how the speaker benefits. Apply the same test to this report. Be especially wary when someone presents an uncertain crisis as certain, then presses you to buy a solution.
When a crypto pitch promises escape from banks or government, check who controls the digital keys used to transfer your assets. Ask what could block withdrawals. In 2022, Ontario’s Capital Markets Tribunal found registration violations by KuCoin’s operators, incorporated in Seychelles and Singapore. Offshore incorporation did not prevent penalties. Check registration and regulator warnings before transferring family money.
Choose Holdings Your Family Can Live With
An index fund can hold hundreds of stocks yet depend heavily on a few large companies. Researchers writing in an August 2026 European Central Bank blog post flagged high U.S. stock valuations and heavy exposure to technology companies. Holding several funds can give the hare a false sense of security. Looking inside those funds, the tortoise checks whether they own the same businesses.
A passive index exchange-traded fund (ETF) follows its index strategy. It accepts the companies and prices built into the index. That is why I question treating it as a complete family solution.
A discretionary portfolio manager can avoid an overpriced stock, limit one industry or hold cash within agreed rules, called the mandate. Your family’s income needs and ability to withstand losses should shape those rules.
The dot-com record shows how widely outcomes can differ. Both tables cover December 31, 1999, to December 31, 2002. Each figure is the cumulative change over those three years.

Canadian financial and energy shares gained while the broad indexes fell. Materials gained much less.
Year-end figures do not show how deep the crash became. From its March 10, 2000 closing peak to its October 9, 2002 closing low, the Nasdaq fell 77.9 percent.

The second table includes reinvested income. The financial fund and selected resource and gold funds gained while the S&P 500 fell. Results also differed widely within resources. The tortoise reads past a sector label to understand the risks in the fund. For a retiring family, what the portfolio owns determines which market setbacks reach the money needed for living costs.
Protect the Returns You Actually Keep
After a sharp fall, the hare sells to stop the discomfort. Once prices recover, buying back feels harder. The tortoise decides in advance how spending needs, valuations and changes in the investments will guide its response.
DALBAR’s 2014 study covered January 1, 1984, to December 31, 2013. Over those 30 years, the S&P 500 returned 11.11 percent a year. DALBAR calculated 3.69 percent a year for the average equity fund investor. The gap was 7.42 percentage points a year. Its research examined monthly fund purchases, sales and switches.
A Real Client Redemption Decision
A client I have worked with instructed an adviser to begin redeeming all private investments then available for redemption. The adviser had already contacted the providers. Concerns about elevated redemption requests had brought a familiar question back to the surface: could the client get the money out before conditions became worse?
In earlier discussions, market declines or uncertainty about access had led this client to favour cash or pause further investment. A decline in a managed portfolio prompted detailed questions about what had happened, whether private-asset valuations were involved and whether the portfolio still fitted retirement and liquidity needs.
Those were sensible questions. The client wanted to understand the structure and the choices available. In previous conversations, clear explanations had helped the client reconsider an initial defensive response and remain invested or reinvest. A new concern could reopen the same questions.
The private holdings were in different circumstances. Some had withdrawal restrictions; some were being wound down. Others were facing redemption pressure while continuing to operate and make distributions. Each required its own review.
I asked the client to assess each investment separately, including its underlying financial condition, redemption terms and role in the overall plan. That review should also establish how much cash is needed, when it must be available and what would happen to any redemption proceeds. The client retained the final decision.
The same decision standard applies here as it did in 1999. Examine the business, the price, the terms and the family’s needs, then act on what you find. Redeem when the facts call for it. Hold or reduce when those choices better serve the plan. The tortoise uses that review to decide. The hare reacts to the headline before establishing which risk the action will solve.
Selling or redeeming creates a second decision: what should the money do next? Proceeds needed for retirement spending or a reserve have a clear purpose. Money intended for reinvestment needs a plan, too. Worse headlines can make returning harder; a recovery can leave an investor deciding whether to buy at higher prices. The tortoise includes the use of the proceeds in the original decision.
Keep Your Family in Charge
I favour discretionary portfolio management within your family’s wider wealth plan. The tortoise chooses what to delegate and sets the manager’s authority. A specialist can manage retirement investments while the family keeps land and business decisions.
Coordinate the portfolio manager with tax, legal and succession experts. Set clear roles around your family’s goals. Retirement, illness or business changes may call for a different mix of assets.
The mandate lets the manager trade without approval for each transaction. Agree on how decisions will be explained and concerns handled. Review costs, withdrawal rights and how to end the relationship. Ask who reviews the manager’s decisions. I favour an investment committee and specialist managers where needed. Use a benchmark, or yardstick, suited to the portfolio’s purpose and risks.
A discretionary mandate also needs to fit the investor’s expectations. If the family wants to direct each move into or out of markets, discuss that before appointing a manager. Agree on what the family controls, what the manager controls and when the mandate should be reviewed.
Spreading risk depends on how assets respond to changing conditions. Stocks and bonds can both fall as inflation and interest rates rise. Inflation also reduces buying power. Liquidity means how easily you can turn an asset into cash at a fair price. Review sale terms before relying on land, businesses or investments to fund spending.
For private investments, ask for the withdrawal terms in writing. How much notice is required? What charges apply? Can payments be delayed or limited? If withdrawals rise sharply, examine cash reserves, debt obligations, underlying asset values and cash flow. Ask how redemptions will be funded and whether assets must be sold. Assess the ability to meet withdrawals separately from the payment of regular distributions. The tortoise reviews each holding against the family’s cash needs. If an investment cannot provide money when the family needs it, its place in the plan must be reconsidered.
Why the Tortoise Wins
Your family’s finish line may be retirement, a stronger business or passing wealth to the next generation. The tortoise keeps that destination in view. Record who can act through illness or death and how control will pass. Make sure they know the plan. Identify the cash needed for estate costs or a farm or business transfer before the family has to raise it under pressure.
The hare measures success by its latest gain. The tortoise measures progress against the family’s needs. It sets aside money for the journey and changes course when the facts warrant it. That is why I back the tortoise to win: its decisions serve a finish line the family has chosen.
Start with the account that pays your family’s bills. Who can use it if you cannot? What happens if access is blocked? Write down the answers before a crisis forces those decisions.
It starts with gold, then extends across the family’s wealth. Peter J. Merrick and I wrote It Starts With Gold™ to bring the consequences of monetary disruption and dependence on financial institutions into a story families can understand. Carry those questions into your bank accounts, portfolio, land, business and succession arrangements.
Continue Your Asset Security Journey™
Every week, The Merrick Spitters Reset Report™ examines structural economic, monetary and financial developments through the lens of history and Asset Security.
Not yet a subscriber?
Subscribe to receive each new Weekly Editorial, independent research and a complimentary PDF copy of It Starts With Gold™.
Subscribe Free + Receive It Starts With Gold™
Already a subscriber?
If this article raised questions about your own wealth, assets or family planning, learn how Adrian helps clients through PFC Wealth Solutions™.
About Adrian C. Spitters and Peter J. Merrick
Adrian C. Spitters, CFP®, FCSI®, CEA
Adrian C. Spitters is a Canadian private wealth advisor with nearly four decades of experience advising business owners, professionals, farmers, retirees and multigenerational families. Raised on a dairy farm in British Columbia’s Fraser Valley, he focuses on Asset Security, wealth preservation and coordinating specialised professionals around one complete family plan. Adrian is co-author of the international bestseller It Starts With Gold™ and publisher of The Merrick Spitters Reset Report™. Read Adrian C. Spitters’ full biography here.
Peter J. Merrick, TEP®
Peter J. Merrick is an international speaker, educator and estate-planning specialist with more than three decades of experience advising business owners, professionals and family enterprises across Canada and the United States. His work focuses on succession planning, long-term wealth preservation and helping families structure and transition wealth across generations. Peter is co-author of the international bestseller It Starts With Gold™ and publisher of The Merrick Spitters Reset Report™. Read Peter J. Merrick’s full biography here.
Disclosures
The Merrick Spitters Reset Report™ publishes education and research separately from the authors’ advisory practices. This article provides general education. Personal investment, legal and tax advice must reflect the family’s circumstances. Professional management can lose money. Past performance does not guarantee future returns. The tortoise-and-hare analogy describes decision habits and promises no return or outperformance.
The 1999–early 2000 client account describes Adrian C. Spitters’ first-hand experience. The tables illustrate selected published sector, index and fund results over calendar years 2000–2002. They are separate from his clients’ portfolios and individual account returns.
Table figures measure cumulative changes from December 31, 1999, to December 31, 2002. The Nasdaq peak-to-trough figure uses the daily closing prices and dates stated. Price changes exclude dividends; total returns include reinvested distributions. Canadian figures use Canadian dollars; U.S. indexes, funds and the Lipper index use U.S. dollars, without currency conversion.
Cumulative figures compound published annual returns or divide ending by starting investment values. Source rounding affects decimals. Fund results include operating expenses and applicable fee waivers, and exclude taxes and new purchase or redemption charges. Fund predecessor histories are identified in the tables and references. Start-to-end gains can include losses within the period.
The Public Order Emergency Commission concluded in 2023 that the threshold for invoking the Act was met. The Federal Court reached a different conclusion, upheld on appeal. As of October 8, 2026, the Supreme Court docket shows the leave applications submitted for consideration, with no decision listed. An account freeze blocks access to deposits. CDIC states that chequing accounts, savings accounts and GICs are excluded from bail-in conversion.
DALBAR estimates investor returns from aggregate fund flows rather than individual account records. Its comparison is with the S&P 500. Fund selection, costs, cash flows and timing affect the gap; the full difference is not a measure of behaviour alone.
Withdrawal rights, fees, timing and termination depend on the investment and account terms. Private assets can be difficult to value or sell. Redemptions can be delayed or restricted. Regular distributions and redemption capacity require separate assessment.
Crypto regulation depends on the jurisdiction, asset and activity. Registration does not guarantee safety. Direct key ownership requires protection against theft, loss and failure to pass access to heirs.
The AI valuation comparison and expectations for winners and project setbacks are the author’s assessments. The BIS figure models capital investment relative to efficient resource use. Sightline Climate’s estimate concerns delivery delays. The Brookings paper is a conference draft.
References
- Andersson, Malin, Johannes Breckenfelder, Stefano Corradin, Kalin Nikolov, and Maria Antonietta Viola. “The AI Boom: Rational Enthusiasm or the Next Dot-Com Bubble?” The ECB Blog, August 17, 2026.
- BlackRock Funds. Annual Report. September 30, 2005. Global Resources Portfolio, 28; note on performance information, 42. Filed with the U.S. Securities and Exchange Commission.
- BMO Capital Markets Investment Strategy Group. 2022 Market Outlook. November 18, 2021. Exhibits 50 and 111, 26 and 46.
- Canada Deposit Insurance Corporation. “Resolution of Large Banks.” Accessed October 8, 2026.
- Canadian Securities Administrators. Investor’s Guide: Cryptocurrencies. Accessed October 8, 2026. See 6–9.
- Canadian Securities Administrators. “Regulation of Crypto Assets.” Last modified April 3, 2024.
- Capital Markets Tribunal. Mek Global Limited (Re), 2022 ONCMT 15. Reasons and decision, June 21, 2022.
- DALBAR. Quantitative Analysis of Investor Behavior 2014. 20th annual report. Advisor edition. 2014. See 2–5 and 10.
- Federal Court of Appeal. Attorney General of Canada et al. v. Canadian Civil Liberties Association et al., 2026 FCA 6. Plain-language decision summary. January 16, 2026.
- Federal Reserve Bank of St. Louis. “NASDAQ Composite (NASDAQCOM).” FRED. Data supplied by Nasdaq, Inc. Daily closing observations for December 31, 1999, and December 31, 2002. Accessed October 8, 2026.
- Hennessy Funds. “Hennessy Small Cap Financial Fund.” Calendar year total returns for Investor Class (HSFNX) and Russell 2000 Index Financials, 2000–2002. Predecessor FBR fund history. Accessed October 8, 2026.
- House of Commons Standing Committee on Finance. Evidence, Meeting 21, 44th Parliament, 1st Session. February 22, 2022. Testimony on account freezes under the emergency measures.
- Merrick, Peter J., and Adrian C. Spitters. It Starts With Gold™. 2025. Book details and complimentary digital edition.
- Ontario Securities Commission Investor Office. “How Exchange-Traded Funds (ETFs) Work.” GetSmarterAboutMoney.ca. Last modified January 2, 2026.
- Ontario Securities Commission Investor Office. “Understanding Real Estate Investments.” GetSmarterAboutMoney.ca. Last modified June 12, 2024.
- Ontario Securities Commission Investor Office. “Why Does Risk Matter in Investing?” GetSmarterAboutMoney.ca. Last modified January 15, 2026.
- Public Order Emergency Commission. “Public Order Emergency Commission Releases Report.” February 17, 2023.
- Rogers, Chris. “Behind the AI Boom: The Electronics Supply-Side Constraints.” S&P Global Market Intelligence, July 28, 2026.
- Rungcharoenkitkul, Phurichai. The AI Investment Race. BIS Working Papers, no. 1367. Bank for International Settlements, July 14, 2026.
- S&P Dow Jones Indices. S&P U.S. Indices Methodology. Accessed October 8, 2026.
- Sprott. “Sprott Gold Equity Fund.” Calendar year total returns for Investor Class (SGDLX) and S&P 500 Total Return Index, 2000–2002. Accessed October 8, 2026.
- Supreme Court of Canada. Attorney General of Canada, et al. v. Canadian Civil Liberties Association, et al. Case 42261. Docket, summary, and lower court rulings. Accessed October 8, 2026.
- U.S. Securities and Exchange Commission. “Investor Alert: Investment Newsletters Used as Tools for Fraud.” June 2, 2014.
- Van Nieuwerburgh, Stijn. Financing the AI Buildout. Brookings Papers on Economic Activity conference draft, September 2026.
- Wang, Olivia. “Data Center Outlook: Half of 2026 Pipeline May Not Materialize.” Sightline Climate, February 24, 2026. Now hosted by Currence.