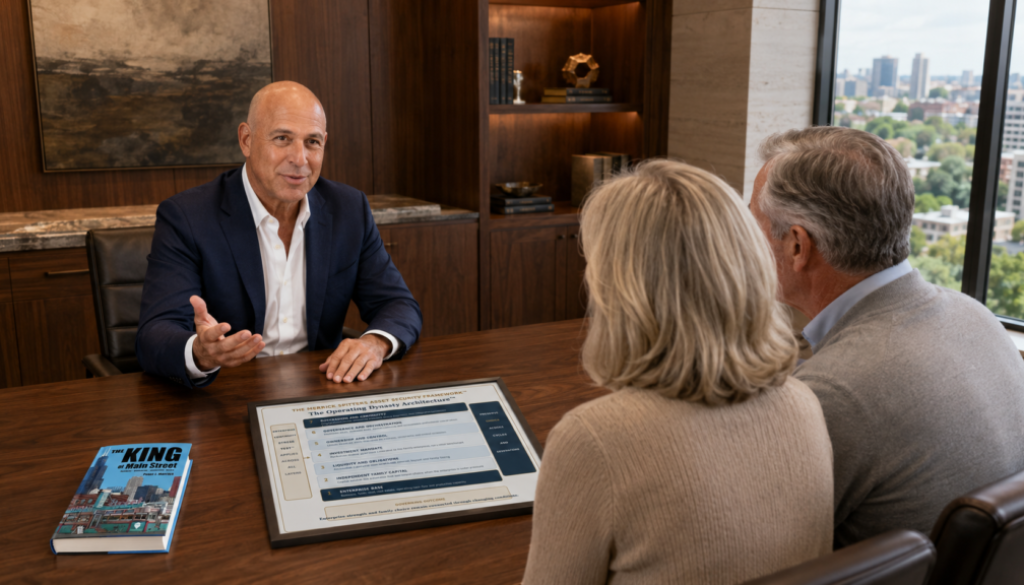
A Diversified Portfolio Cannot Protect an Undiversified Family Balance Sheet
Why operating families must coordinate business risk, financial capital, liquidity, governance and succession as one structure
By Peter J. Merrick, TEP® and Adrian C. Spitters, CFP®, FCSI®, CEA
Co-Authors, It Starts With Gold™ | Co-Creators, The Merrick Spitters Reset Report™
Peter J. Merrick is also the author of The King of Main Street, the book featured in this article.
When Business Success Concentrates Family Risk
In The King of Main Street, Michael builds a seniors’ residence company from a determined idea into a major enterprise. He keeps control, borrows to grow and puts much of the available cash back into the business. Those choices help create his success. They also leave his family wealth tied to the same company, the same cash flow and many of the same risks.
Michael’s story reflects a truth we often see among business owners, farmers and families with valuable real estate. The asset that creates the wealth also becomes the source of income, the base for borrowing and the plan for retirement. It may even be expected to fund tax, support the next generation and provide a future inheritance.
The family may also own a portfolio of stocks, bonds, cash and several investment managers. By the usual measures, that account may be well diversified. Yet the statement does not show the operating company, the property pledged against debt, the personal guarantees, the future tax bill or the people who depend on the enterprise.
The investment account may be diversified. The family may not be.
That is the central problem in this article. A portfolio can spread investment risk inside an account. It cannot, by itself, protect a family whose business, income, property, debt, liquidity and succession plan all depend on the same outcome.
The Statement Is Not the Balance Sheet
Portfolio diversification remains useful because it can reduce avoidable exposure to one company or industry, but it answers a narrow question. It shows how investments are spread across asset classes, sectors, regions and securities.
An investment statement cannot show the whole family balance sheet. For an operating family, the largest asset may be a business, farm, landholding or private real estate company. That asset may provide income, support borrowing and fund retirement or estate plans.
A family can therefore own hundreds of securities and still depend on one enterprise, lender, property market or succession outcome. Diversifying an account is not the same as securing the family balance sheet.
What Institutional Discipline Gets Right
Research on pension funds, family offices and other large investment institutions reaches a simple conclusion. Large investors do not rely on a secret list of investments. They rely on a disciplined process.
They begin with risk management, use committees, seek truly different sources of return, review specialist managers carefully and rebalance according to policy. These habits create debate, accountability and patience. They also help keep emotion from setting the investment plan.
The research also asks a basic question: do assets with different names truly behave differently? Since 2020, stocks and bonds have increasingly moved together during periods of sharp market stress, weakening the protection traditionally expected from a conventional 60/40 portfolio. Bonds can still provide useful diversification. The lesson is that protection must be tested before a family relies on it.
Even excellent portfolio discipline has a boundary. It can govern stocks, bonds, private debt and real estate funds without seeing that a family business, guaranteed debt, commercial property and succession plan all depend on the same credit cycle. Operating families need a structure that connects the portfolio to everything around it.
Different Assets Can Carry the Same Risk
A business owner may hold an operating company, the building it occupies, a public-market portfolio and a home. On paper, these are four assets. In practice, all four may depend on affordable credit, steady demand, reliable cash flow and confident buyers.
If credit tightens, the business may face higher costs, the property may become harder to refinance, public markets may reprice debt-sensitive companies and the home may take longer to sell. The owner may need more cash inside the business at the same time that outside assets are losing value.
Farming and real estate families face similar connections. Land, equipment, development projects and financial holdings may all react to interest rates, input costs, commodity prices, construction costs or the availability of buyers.
Asset count is not the same as economic diversification. Ten holdings do not create ten sources of strength when all ten require the same conditions to succeed.
Why This Matters Across North America
This challenge affects operating families throughout Canada and the United States. Both economies depend heavily on private businesses, farms, real estate and family-owned enterprises.
Canadian families often hold much of their net worth in a private company, farmland or real estate. A conventional Canadian portfolio may add exposure to the same banks, industries and economy that support those operating assets.
American families may have access to broader capital markets and more investment choices, but the same structural problem remains. A business can still depend on one region, customer group, credit cycle or founder. Legal rules may differ, but no document can create liquidity that was never funded or leadership that was never prepared.
Cross-border families add currency, residency, tax and estate questions. The details differ between Canada and the United States. The need for coordination does not.
The Hidden Link Between Income and Capital
For many operating families, the same asset provides current income and holds much of the family’s long-term capital. When the enterprise struggles, salary, dividends, retained earnings, property value and the expected sale price may all come under pressure together.
This is why we distinguish market value from financial security. An asset can be valuable without being liquid. It can be profitable without being easy to transfer. It can support one household today without being able to support two family branches tomorrow.
The balance sheet may look strong in dollars while offering very little room to move.
The Main Street Builder’s Paradox
Michael prefers debt to selling equity because ownership gives him more than a financial interest. It allows him to shape the company, protect its purpose and decide how it will grow. Many business owners and farming families understand that instinct. Their enterprise reflects their work, judgment, relationships and identity.
Yet the same decision that protects control can also concentrate risk. Debt creates fixed payments, lender conditions and refinancing dates. Personal guarantees connect company borrowing to family assets. Reinvesting most available capital can leave too little independent liquidity outside the business.
This is the Main Street builder’s paradox. The habits that create enterprise wealth can also make the family less secure. Concentration may be necessary while a company is being built. It becomes dangerous when a high valuation or easy credit is mistaken for lasting financial strength.
Michael’s experience also separates cash flow from durable family wealth. Enterprise income is not the same as capital that remains independent, accessible, transferable and able to survive without the founder.
Liquidity Is What Preserves Choice
Liquidity often receives less attention than investment return because it appears unproductive during good times. Cash earns less than an operating company is expected to earn. Insurance funding, credit reserves and short-term holdings may seem conservative when sales are strong and financing is easy.
Their value becomes clearer when circumstances change.
A family may need capital to carry inventory, repair equipment, settle tax, support a surviving spouse, buy out a sibling, retain key employees or wait for a better time to sell. If liquid resources are not available, a valuable long-term asset may have to be sold under short-term pressure.
That is The Liquidity Gap™: the distance between the wealth a family appears to own and the cash it can actually access when a decision must be made.
The purpose of liquidity is not to predict the next recession or market decline. It is to prevent someone else from setting the family’s timetable. A lender, buyer, tax authority or urgent family need gains power when the family has no time.
Michael later builds part of his fortune by purchasing valuable properties from companies facing short-term cash pressure. Those sellers do not necessarily lack good assets. They need to reduce debt, meet payments or fund payroll before their own timetable allows. Their liquidity problem becomes his opportunity. The story captures a hard truth: a strong asset sold under pressure can create wealth for the buyer while destroying value for the owner who could not wait.
Liquidity preserves time. Time preserves negotiating power. Negotiating power preserves choice.
Risk Is Timing Vulnerability
Most investors are taught to think of risk as volatility. If markets fall, they are told to remain patient and wait for recovery. That advice can be reasonable when income continues, time is available and no major obligation must be funded during the decline.
Operating families do not always control the timing. A refinancing date arrives when it arrives. Payroll cannot wait for a market recovery. A tax obligation may follow a death or transfer. A buyout may be triggered by an agreement. A family member may need to be equalized. A lender may reduce an available facility just as the enterprise needs more working capital.
This is the deeper risk identified in What Smart Capital Builders and Stewards Know About Risk: timing compression combined with liquidity insufficiency. Market volatility is the visible event. The structural danger is the loss of time and choice.
Risk rises when several demands arrive together. Credit becomes restrictive. Asset values soften. Succession work remains unfinished. Liquid capital is insufficient. The family may still have substantial net worth, but its decision space begins to narrow.
That narrowing creates what we call Succession Compression™.
Succession Is a Balance-Sheet Event
Succession is often discussed as a future legal or family matter. In reality, it is also a present capital-allocation decision.
If one child will operate the business and another will not, how will value be divided without weakening the enterprise? If the founder wants income after stepping back, where will it come from? If tax becomes payable, which asset will fund it? If the successor needs to borrow heavily to purchase the company, will the debt leave enough room for the business to survive a difficult cycle?
These are not separate questions. They connect ownership, liquidity, fairness, control and the future earning capacity of the enterprise.
A will can state who receives an asset. It cannot ensure that the recipient is prepared to govern it. A shareholders’ agreement can define rights. It cannot guarantee that the company will have enough cash to honour them. Insurance can provide capital. It cannot resolve an unspoken conflict about leadership or fairness.
A strong succession plan therefore has to coordinate the legal structure with the economic structure. It must consider who owns, who controls, who leads, who receives income, who assumes risk and where the required liquidity will come from.
Succession begins long before ownership changes. It begins when the family decides whether the balance sheet is being built only for the founder’s working life or for continuity beyond it.
The King of Main Street places this contrast directly in front of Michael. In the story, Richard prepares his successor, Mitch, over many years through mentorship, trust and shared work. When Richard later dies, Mitch is able to step forward because the preparation began before the transition was forced upon him. Michael, by contrast, believes he will not need to worry about his own succession for a long time. The reader can see the danger before he does. Time passes while the founder remains focused on growth.
The lesson is not that every child must inherit the enterprise. It is that every operating family must decide what continuity means before age, illness, death or family conflict makes the decision for them. Succession planning is the conversion of responsibility from one generation into preparedness in the next.
Governance Becomes More Important as Wealth Grows
Complexity tends to increase faster than clarity. One successful business may lead to real estate, holding companies, trusts, investment accounts, insurance policies and new ventures. Family members may take on different roles. Advisors may each understand one part of the structure without seeing the whole.
The family can become wealthier while becoming harder to coordinate.
Governance is the discipline that connects decisions to purpose. It establishes who receives information, who has authority, how major decisions are made, how conflicts are addressed and how the next generation learns to become an owner rather than simply an heir.
Good governance does not require a family constitution for every household. It begins with simpler habits: a consolidated view of assets and obligations, clear decision rights, regular communication, documented responsibilities and an agreed process for reviewing risk.
Without those habits, individual decisions may be reasonable on their own but harmful when combined. One advisor may recommend more market exposure. Another may arrange additional debt. A lawyer may restructure ownership. An accountant may reduce current tax. Each decision may solve a local problem while increasing the family’s dependence on a single future outcome.
The book describes the need for a trusted coordinator who can see how specialized work fits together. That idea is important, but it must be applied with clear professional boundaries. The coordinator does not replace the accountant, lawyer, portfolio manager, insurance advisor or lender. The role is to keep the shared facts, family objectives, responsibilities and timing visible so each independent specialist can do the right work in the right sequence.
Michael eventually learns a similar lesson inside his company. After years of carrying too much personally, he delegates to experienced people, defines what qualifies them for responsibility and allows a stronger organization to emerge around him. Governance begins when the enterprise no longer depends on the founder remembering, approving and carrying everything alone.
The Stress Test Beneath an Operating Family
The Merrick Spitters Asset Security Framework™ is the umbrella framework. The Operating Dynasty Architecture™ coordinates the family-enterprise structure, while the remaining models examine specific dependencies within it.
For families whose wealth is concentrated in a business, farm, land, real estate or closely held enterprise, The Operating Dynasty Architecture™ connects the enterprise, family capital, liquidity, governance and succession as one coordinated structure.
It brings the enterprise, family capital, liquidity, investment mandates, legal control, governance and succession into one view. The purpose is to preserve choice through credit cycles and across generations. Within The Operating Dynasty Architecture™, The Enterprise Continuity Stress Test™ provides the diagnostic starting point.
The Enterprise Continuity Stress Test™ asks whether a concentrated family enterprise can preserve control when tighter credit, weaker markets, urgent cash needs and succession pressure occur together.
It begins with The Dual Balance Sheet Concept™. One side contains the enterprise assets that create family wealth. The other contains independent family capital, including liquid reserves, financial investments, insurance values and other resources that may remain available when the enterprise is under pressure.
The Liquidity Gap™ applies that analysis to expected obligations. Succession Compression™ tests whether the work required to align ownership, leadership, legal documents, family expectations and funding is greater than the time available.
The Central Orchestration Model™ assigns responsibility for keeping the family, enterprise and independent professionals aligned around the same facts and priorities.
Together, these tools form a clear sequence: see the whole balance sheet, test its liquidity, examine the time available for succession and assign responsibility for coordination. The Merrick Spitters Asset Security Framework™ then guides implementation without turning the process into another investment product or replacing independent professional advice.
A Better Definition of Diversification
True diversification should not be measured only by the number of investments in an account. It should be measured by the number of genuinely independent sources of strength available to the family.
Does the family have capital outside the operating enterprise? Can that capital remain available if the business needs support? Are liquidity reserves protected from the same risks affecting the main asset? Does the investment portfolio behave differently from the business, property and debt structure? Can the family meet tax and succession obligations without a forced sale? Are leadership and decision-making able to continue if the founder is absent?
These questions do not produce a single ideal allocation. A farmer, manufacturer, developer and professional practice owner will not hold the same assets or face the same risks. The goal is to identify where different parts of the family structure depend on the same assumption and decide whether that dependence is acceptable. Some concentration may be necessary to build a successful enterprise. The danger arises when wealth, income, debt and decision-making remain concentrated without enough liquidity or a plan for continuity.
The Questions Worth Asking Now
A family does not need to wait for a sale, illness, credit event or conflict before examining its structure. The best time to review it is often while the business is healthy and choices remain open.
Start with one picture of the operating company, real estate, land, guarantees, debt, investments, insurance, expected tax and family cash needs. Then identify the conditions that support each asset and obligation.
Ask where cash would come from if the family needed time. Which resources can be used without damaging the enterprise? Which require a willing buyer or a new loan? Which may disappear during the same conditions that create the need?
Finally, examine control and succession. Identify who can make decisions today, who could make them tomorrow and whether the planned transfer has enough capital, information and prepared leadership.
The goal is not to remove uncertainty. It is to keep uncertainty from removing every good option at once.
A Portfolio Is a Component, Not a Shield
A diversified portfolio remains an important part of sound wealth planning. But it should be understood for what it is: a component of the family’s financial structure, not a shield around everything else the family owns.
Operating families build wealth through commitment. They concentrate time, capital, reputation and often several generations of effort in an enterprise. That concentration can create extraordinary value. It can also make the family vulnerable when income, capital, debt, liquidity and succession all depend on the same outcome.
The answer is not to abandon the enterprise that created the wealth. It is to build a structure around it that can carry the family through changing markets, changing leadership and changing generations.
The strongest family balance sheet is not the one with the most assets. It is the one that preserves the greatest range of choices when conditions no longer unfold as expected.
Continue Your Asset Security Journey™
Every week, The Merrick Spitters Reset Report™ examines structural economic, monetary and financial developments through the lens of history and Asset Security.
Not yet a subscriber? Subscribe to receive each new Weekly Editorial, independent research and a complimentary digital copy of The King of Main Street by Peter J. Merrick.
Subscribe Free + Receive The King of Main Street
If you prefer to purchase a copy, The King of Main Street is available through your preferred Amazon marketplace:
Reading the story is only the beginning. Its practical value lies in the questions it prompts an owner to address before circumstances narrow the available choices.
Already a subscriber? If this article raised questions about whether your business, investments, liquidity and succession plan are working as one structure, learn how Adrian helps clients through PFC Wealth Solutions™.
About the Authors and Publishers
Peter J. Merrick, TEP® is the author of The King of Main Street and an independent specialist in succession, estate and cross-border planning. He is a co-founder of The Merrick Spitters Reset Report™ and works with business-owning families on the transfer of ownership, control and responsibility across generations.
Adrian C. Spitters, CFP®, FCSI®, CEA is President and Private Wealth Advisor at PFC Wealth Solutions™ and a co-founder of The Merrick Spitters Reset Report™. He has worked with families, business owners and investors since 1987, helping them examine wealth through the lens of Asset Security, structure and long-term stewardship.
Together, Adrian and Peter are co-authors of It Starts With Gold™ and joint owners and publishers of The Merrick Spitters Reset Report™.
Disclaimer
This article is published for general educational and informational purposes only. It does not provide individualized investment, securities, insurance, financial, legal, tax or accounting advice and does not constitute an offer, solicitation, or recommendation to buy, sell or hold any investment, security, insurance product or financial strategy. Examples are illustrative. Historical data, correlations and past performance do not guarantee future results. Readers should obtain advice from appropriately qualified independent professionals who understand their circumstances before acting. Reading or subscribing does not create a professional, advisory, fiduciary or client relationship.
References
- Adrian, Tobias, Johannes Kramer, and Sheheryar Malik. “Stock-Bond Diversification Offers Less Protection from Market Selloffs.” IMF Blog, February 18, 2026. Accessed August 31, 2026.
- Board of Governors of the Federal Reserve System. Changes in U.S. Family Finances from 2019 to 2022: Evidence from the Survey of Consumer Finances. October 18, 2023. Accessed September 4, 2026.
- Canadian Federation of Independent Business. Succession Tsunami: Preparing for a Decade of Small Business Transitions in Canada. January 10, 2023. Accessed September 4, 2026.
- Innovation, Science and Economic Development Canada. Key Small Business Statistics 2024. 2024. Accessed September 4, 2026.
- Merrick, Peter J. The King of Main Street: Business – Mentorship – Succession – Legacy. King of Main Street Publishing Limited, 2019.
- Merrick, Peter J., and Adrian C. Spitters. “What Smart Capital Builders and Stewards Know about Risk.” The Merrick Spitters Reset Report™, March 2, 2026. Accessed August 30, 2026.
- Organisation for Economic Co-operation and Development. Strengthening the Application of OECD Core Principles of Private Pension Regulation: Lessons from Investment Institutions. In OECD Pensions Outlook 2018. 2018. Accessed September 4, 2026.
- Statistics Canada. The Assets, Debts and Net Worth of Canadian Families, 2023. October 29, 2024. Accessed September 4, 2026.
- Spitters, Adrian C., and Peter J. Merrick. Succession Compression™. The Merrick Spitters Reset Report™, 2026. Accessed September 4, 2026.
- Spitters, Adrian C., and Peter J. Merrick. The Central Orchestration Model™. The Merrick Spitters Reset Report™, 2026. Accessed September 4, 2026.
- Spitters, Adrian C., and Peter J. Merrick. The Dual Balance Sheet Concept™. The Merrick Spitters Reset Report™, 2026. Accessed September 4, 2026.
- Spitters, Adrian C., and Peter J. Merrick. The Enterprise Continuity Stress Test™. The Merrick Spitters Reset Report™, 2026. Accessed September 4, 2026.
- Spitters, Adrian C., and Peter J. Merrick. The Liquidity Gap™. The Merrick Spitters Reset Report™, 2026. Accessed September 4, 2026.
- Spitters, Adrian C., and Peter J. Merrick. The Merrick Spitters Asset Security Framework™. The Merrick Spitters Reset Report™, 2026. Accessed September 4, 2026.
- Spitters, Adrian C., and Peter J. Merrick. The Operating Dynasty Architecture™. The Merrick Spitters Reset Report™, 2026. Accessed September 4, 2026.
- U.S. Small Business Administration, Office of Advocacy. 2025 Small Business Profile. June 2025. Accessed September 4, 2026.
- UBS. Global Family Office Report 2025. May 2025. Accessed September 4, 2026.